 Auto Approve Loans
A fender bender raises a quick money question: pay the body shop yourself or file an insurance claim? At Auto Approve, a free matching service where participating lenders make every credit decision, we hear this question constantly, and the honest answer depends on four numbers: the repair estimate, your deductible, your likely premium increase and the cash you have on hand.
This guide walks through how to weigh those numbers, when paying directly is the smarter move, when a claim protects you better, and how drivers without enough savings sometimes use a small personal loan to cover a minor collision repair without touching their insurance record.
When Does Paying Out of Pocket for a Fender Bender Make Sense?
Paying out of pocket makes sense when the repair estimate is close to or below your deductible, nobody was hurt, you caused the damage, and a claim would likely raise your premium for several years.
The logic is simple. Your insurer pays only the amount above your deductible. If your deductible is $1,000 and the bumper repair costs $1,200, a claim recovers just $200. In exchange, an at-fault claim can add a surcharge to your premium that often lasts three to five years, depending on your state and insurer. Paying that $1,200 yourself can easily cost less than the claim over time.
Paying directly also tends to fit when:
- The damage is cosmetic, such as a scuffed bumper cover, a small dent or scratched paint.
- Only your car was involved, for example a low-speed bump against a pole or garage door.
- You already have one claim on your record and want to avoid a second.
- The repair estimate comes in under about $1,500 and you can cover it without missing rent or bills.
What Does a Typical Fender Bender Repair Cost?
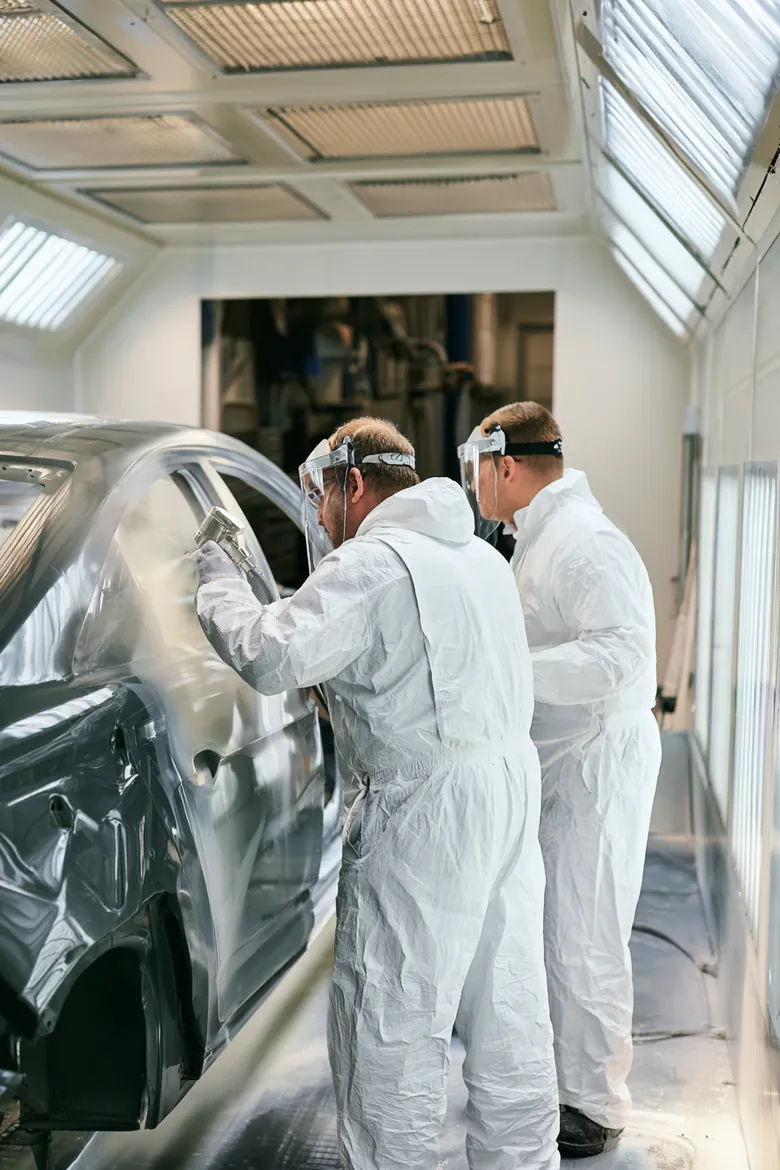
A typical fender bender repair costs roughly $300 to $1,500 for minor bumper or dent work, while repainting a single panel often runs about $400 to $1,000 depending on color, finish and shop rates.
Costs climb quickly once damage goes beneath the surface. A modern bumper may hide parking sensors, radar units for adaptive cruise control or camera brackets that need recalibration after a repair. A simple scratch can turn into a $2,000 job when sensors, clips and an absorber pad all need replacement. That is why we always suggest getting a written estimate before deciding anything.
| Repair | Typical estimated range | Notes |
|---|---|---|
| Paintless dent repair (small dent) | About $100 to $450 | Works when paint is not cracked |
| Bumper scuff and scratch repair | About $300 to $700 | Sanding, filling and blending paint |
| Bumper cover replacement | About $600 to $1,500 | Higher with sensors or premium paint |
| Single panel repaint | About $400 to $1,000 | Color matching affects the price |
| Headlight or taillight assembly | About $200 to $1,200 | LED and adaptive units cost more |
| Sensor or camera recalibration | About $150 to $500 | Often required after bumper work |
These are estimates only. Shop labor rates, paint type and the age of your car all move the final number up or down.
How Your Deductible Changes the Math
Your deductible sets the floor for any claim payout, so the gap between the repair estimate and the deductible is the real value of filing. A small gap usually means paying out of pocket is cheaper.
Collision deductibles are commonly $500 or $1,000. Here is how the same repair looks under each one:
- $900 repair, $500 deductible: the insurer pays about $400. A premium increase could erase that within a year.
- $900 repair, $1,000 deductible: the insurer pays nothing. A claim would only add a mark to your record.
- $2,500 repair, $500 deductible: the insurer pays about $2,000. A claim is much more likely to be worth it.
- $2,500 repair, $1,000 deductible: the insurer pays about $1,500. Compare that against a few years of possible surcharges.
If you do file and need help covering the deductible itself, our guide on using a personal loan for a car insurance deductible explains the trade-offs in detail.
How Much Could a Claim Raise Your Premium?
An at-fault collision claim can raise a car insurance premium noticeably, and the surcharge commonly stays on your policy for about three to five years, so the true cost of a claim is spread over several renewals.
Exact increases vary widely by state, insurer, driving record and the size of the claim, and some states limit surcharges for small claims. Rather than guessing, ask your agent a direct question: "If I file a collision claim of this size, how would my premium change at renewal?" Many agents can answer without opening a claim.
A simple way to test the decision is to multiply the likely yearly increase by the number of years it lasts. If your premium might rise by $300 per year for three years, the claim costs about $900 in extra premiums. If the insurer would pay only $400 toward the repair, paying out of pocket wins by roughly $500. Losing a claims-free discount can widen that gap further.
When Filing an Insurance Claim Is the Better Choice
Filing a claim is usually the better choice when anyone might be injured, another driver caused the accident, the damage is well above your deductible, or hidden structural damage could appear later.
Specific situations where a claim tends to protect you:
- Possible injuries. Even mild neck pain can turn into medical bills. Paying privately offers no protection if the other party later seeks compensation.
- The other driver was at fault. Their liability coverage should pay for your repair, and you may owe no deductible at all.
- Damage above about $2,000. The payout usually outweighs a few years of surcharges.
- Frame, airbag or suspension damage. Costs can escalate past $5,000 once the shop takes the car apart.
- A disagreement about what happened. An insurer handles the dispute and documentation for you.
Never make a private cash deal with another driver without documenting it in writing. If they change their mind later, you may have little evidence of what was agreed.
What Steps Should You Take Right After a Minor Collision?
Right after a minor collision, check for injuries, move to a safe spot, exchange information, photograph everything and get at least one written repair estimate before deciding how to pay.
- Check on everyone. Call for help if anyone is hurt, and call police if your state or city requires a report.
- Exchange details. Get names, phone numbers, insurance companies, policy numbers and plate numbers.
- Take photos. Capture both cars, the road, signs and any skid marks from several angles.
- Review your policy. Look up your collision deductible and the reporting requirements.
- Get estimates. Two or three written estimates from body shops help you spot overpricing.
- Decide with numbers. Compare the estimate, deductible and possible premium change before calling to open a claim.
How to Pay for a Fender Bender When Savings Fall Short
When savings fall short, drivers commonly combine part of their cash with a shop payment plan, a credit card or a small personal loan, choosing the option with the lowest total cost they can comfortably repay.
Options worth comparing:
- Emergency savings. The cheapest option because there is no interest. Our guide on building an emergency car fund helps you prepare for the next one.
- Body shop payment plans. Some shops split a bill into two or three payments. Ask about fees and due dates.
- Credit cards. Fine if you can pay the balance quickly or have a promotional rate. Standard card APRs can be high if a balance lingers.
- Personal loans. A fixed-rate installment loan with a set end date, which helps some borrowers budget.
A personal loan is not right for everyone. If your income is unstable, or the repair is optional and can wait, waiting and saving is often wiser than borrowing.
Using Auto Approve to Compare Personal Loan Offers for Collision Repair
Auto Approve lets you submit one short request that may be shared with participating lenders, who review it, decide whether to make an offer and set any APR and terms. Not every applicant is approved.
Our matching service does not lend money or make credit decisions. Auto loan approval for repair costs depends on each lender's review of your credit, income and state rules. Personal loans in the $500 to $5,000 range typically carry APRs from about 6% to 35.99%, with terms commonly from 3 to 36 months. If approved, some lenders can send funds as soon as the next business day, though timing depends on the lender and your bank.
You can read more about borrowing for body damage on our collision repair loans page, and compare typical pricing on the personal loan rates page before you request offers.
What Would a Small Personal Loan for a Fender Bender Cost?
A small personal loan for a fender bender usually costs tens to a few hundred dollars in interest, depending on the amount, the APR the lender offers and how many months you take to repay it.
| Loan amount | APR and term | Estimated monthly payment | Estimated total interest |
|---|---|---|---|
| $500 | 24% for 6 months | $89.26 | $35.58 |
| $1,000 | 12% for 12 months | $88.85 | $66.19 |
| $1,000 | 24% for 12 months | $94.56 | $134.72 |
| $1,500 | 24% for 12 months | $141.84 | $202.07 |
| $2,000 | 24% for 12 months | $189.12 | $269.43 |
| $2,000 | 35.99% for 12 months | $200.91 | $410.97 |
Representative example: a $2,000 personal loan repaid over 12 months at 24% APR would cost about $189.12 per month, or $2,269.43 in total ($269.43 in interest). This is an estimate; your actual rate and terms are set by the lender.
Compare that interest with the premium increase a claim might trigger. If borrowing $1,000 costs about $134.72 in interest while a claim might add $900 in premiums over three years, the loan may be the cheaper path. Run your own numbers with our personal loan calculator.
Common Mistakes Drivers Make After a Fender Bender
Common mistakes include skipping the written estimate, assuming damage is cosmetic, settling privately without paperwork, filing a tiny claim on reflex and borrowing more than the repair actually requires.
- Accepting the first quote. Prices for the same bumper repair can vary by hundreds of dollars between shops.
- Ignoring hidden damage. Ask the shop to check sensors, brackets and the bumper absorber before you commit.
- Waiting too long to report. Late reporting can complicate coverage if the incident grows into a claim.
- Borrowing the maximum. Request only what the approved auto repair estimate requires. Every extra dollar adds interest.
- Choosing the longest term by default. Lower monthly payments over 18 months can cost noticeably more in total than 12 months.
A Quick Decision Checklist
A quick checklist helps: confirm no injuries, get the written estimate, subtract your deductible, ask your agent about premium impact, then compare that net figure against what paying directly would cost you.
- Was anyone hurt, or is fault disputed? If yes, lean toward a claim.
- Is the estimate less than your deductible plus about $500? If yes, lean toward paying directly.
- Would a claim likely raise your premium for three or more years? Multiply that cost out.
- Can you cover the repair from savings without missing essential bills?
- If not, would a short shop plan or small loan cost less than the expected premium increase?
- Is the repair needed for safety or to pass inspection, or can it wait while you save?
Working through those six questions takes about fifteen minutes and usually makes the right answer clear.
What Do Auto Approve Reviews Say About Borrowing for Small Repairs?
Auto Approve reviews from borrowers often mention the value of comparing more than one offer and of borrowing only what the repair estimate requires, rather than accepting the first figure a lender suggests.
Borrowers who share their stories on our borrower reviews page tend to describe the same habits: they got written estimates, checked the total cost of each offer and chose terms they could repay early. Those habits apply whether you pay cash, use a card or take out a personal loan for a dent or bumper repair.
In my years editing consumer-lending coverage, the drivers who came out ahead after a fender bender were rarely the ones with the most money. They were the ones who paused, gathered three numbers and compared them before making a phone call to their insurer or a lender.
The Bottom Line on Paying for a Fender Bender Yourself
Paying for a fender bender yourself is often smart for small, cosmetic, single-car damage near your deductible, while claims protect you better when injuries, another driver's fault or large repair bills are involved.
Whichever path you choose, start with a written estimate and an honest look at your budget. If you decide a small loan is the best way to bridge the gap, compare offers carefully, read every term, and remember that lenders, not Auto Approve, decide whether to approve a request and on what terms.
Frequently Asked Questions
How much more than my deductible should a fender bender cost before I file a claim?
A common rule of thumb is to consider a claim only when the repair estimate exceeds your deductible by at least $500 to $1,000. Below that gap, the money you receive from the insurer may be smaller than the extra premium you could pay over the next three years if your rate rises after an at-fault claim.
Do I have to tell my insurer about a fender bender I pay for myself?
Many auto policies require you to report any accident promptly, even if you never file a claim. Reporting is not the same as claiming, and a report alone often does not change your rate. Read the notice section of your policy or call your agent, because failing to report can create problems if the other driver later claims an injury.
Can I split a fender bender repair between savings and a small loan?
Yes. Many drivers cover part of a repair from savings and borrow only the remainder, which keeps the loan amount and total interest lower. A $500 loan at 24% APR over 6 months costs about $35.58 in interest, an estimate, while a larger balance would cost more. Lenders set the actual rate and terms.
Related Posts
Secured vs Unsecured Personal Loans for Collision Repair: Which Fits?
Auto Approve finds that for most collision repairs under $5,000, an unsecured personal loan fits best because nothing you own…
Personal Loan vs Credit Card for Car Repairs: Which Costs Less?
For car repairs you cannot pay off within a month or two, a fixed-rate personal loan usually costs less than…
